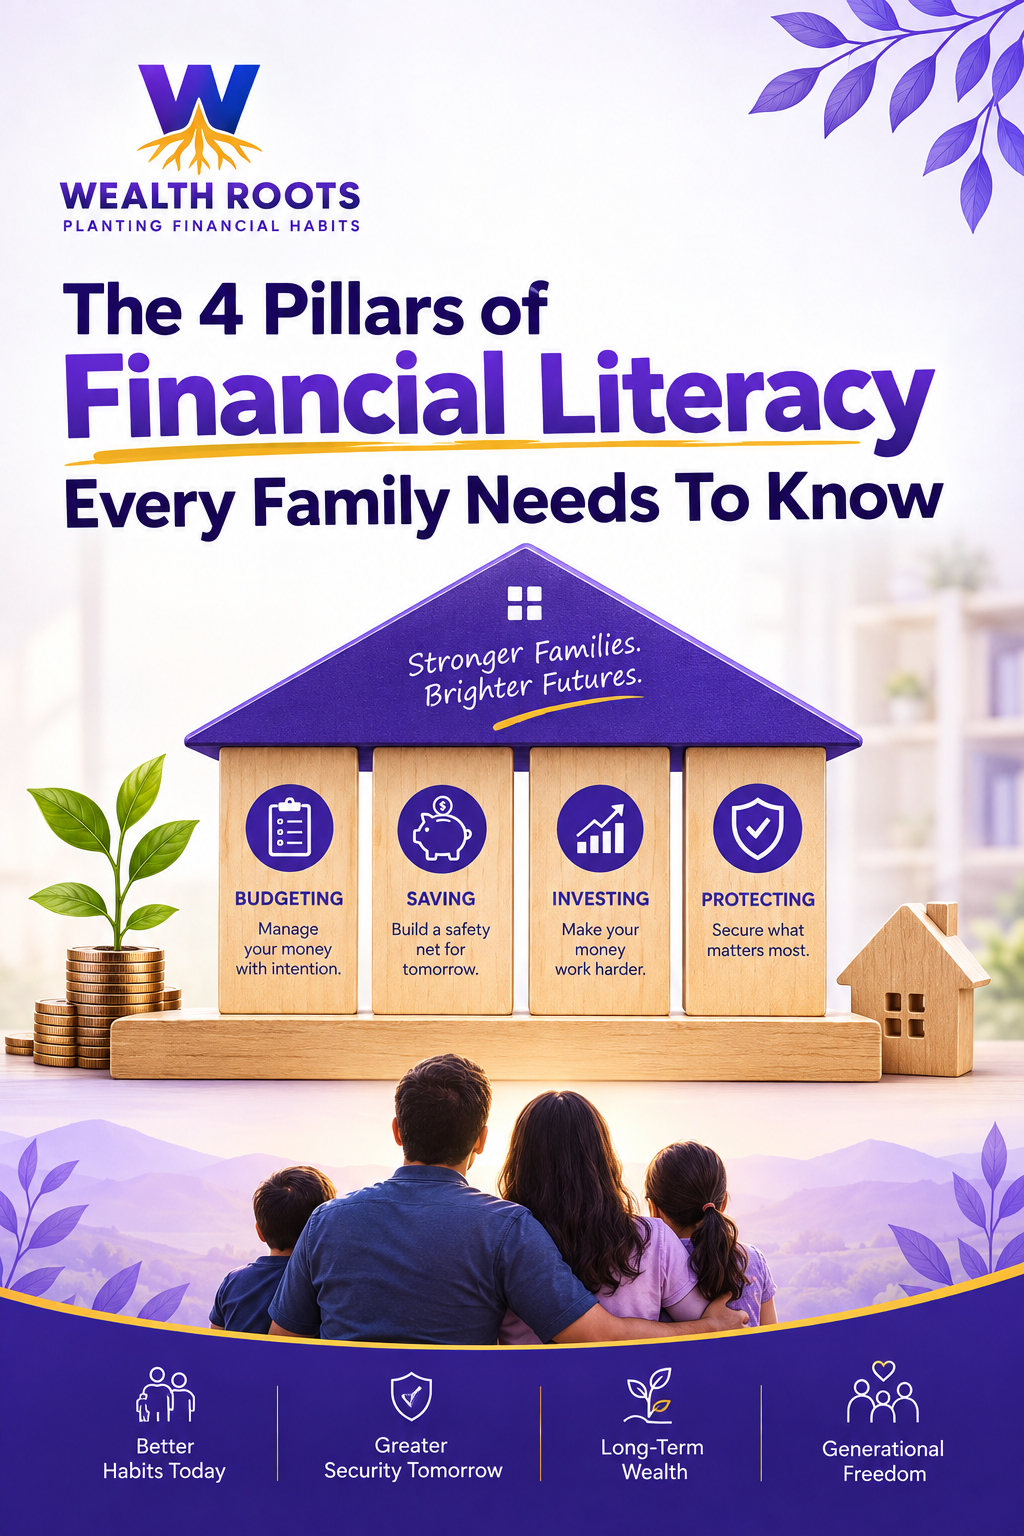
The 4 Pillars of Financial Literacy Every Family Needs To Know
Introduction
Picture the most financially secure family you know. They are not necessarily the richest. They probably don't drive the flashiest car or live in the biggest house. But they never seem to panic over unexpected expenses. They are not drowning in debt. Their children grow up understanding that money is a tool, not a mystery. And somewhere along the way, they built a financial life that actually holds.
What is their secret?
In most cases, it is not luck or a particularly high income. It is the consistent practice of the 4 pillars of financial literacy — budgeting, saving, investing, and protecting. These four pillars, when understood and applied together, form the complete architecture of a financially secure family.
Remove any one of them, and the structure weakens. Build all four, and you create the foundation for not just your own security, but generational financial security — wealth and habits that pass from one generation to the next.
Let us walk through each one.
Pillar 1: Budgeting
Managing what comes in and what goes out
A budget is not a punishment. It is a plan. And yet most Indian families manage money without one — reacting to expenses as they arrive rather than directing money with intention.
The most widely recommended starting point for budget planning is the 50/30/20 rule: 50% of your take-home income goes to needs (rent, groceries, utilities, school fees), 30% to wants (dining out, entertainment, travel), and 20% to savings and investments. It is not a rigid law — it is a compass.
For families with irregular income, a zero-based budget works better: every rupee earned is assigned a job — spending, saving, or investing — until nothing remains unaccounted for.
Good budgeting also means tracking. Even a simple notebook or a free app that logs daily expenses for one month will reveal patterns most families are shocked by: how much quietly disappears on food delivery, impulse purchases, or subscriptions nobody uses anymore.
A budget does not restrict your freedom — it tells your money where to go, instead of wondering where it went.
Pillar 2: Saving
Building safety before building wealth
Most people save what is left after spending. The second pillar of financial literacy insists on doing it the other way around: spend what is left after saving. This is the principle of paying yourself first — and it changes everything.
Before any savings goal, every family needs an emergency fund: three to six months of living expenses, kept liquid and untouched in a savings account or short-term fixed deposit. This single safety net prevents a medical emergency, job loss, or sudden repair from becoming a debt crisis.
Beyond the emergency fund, saving becomes goal-based:
A child's education fund is started when they are young and compounded over 15 years
A home down payment fund, built steadily over three to five years
An annual vacation fund, so holidays are enjoyed without credit card guilt
You do not need to earn a lot to save meaningfully. You need to start.
For example: A SIP (Systematic Investment Plan) of ₹500 per month begun at age 25 invested at 12% annually, grows to over ₹17 lakhs by retirement. The same amount, starting at 35 age, grows to just ₹5 lakhs. The gap is not the amount — it is the time.
The power of compounding rewards those who start early and stay consistent.
Pillar 3: Investing
Making your money work harder than you do
Saving keeps money safe. Investing makes it grow. And in an economy where inflation quietly raises the cost of everything year after year, money that is not growing is effectively shrinking. This is why the third pillar — investing — is not optional for any family that wants long-term financial security.
Starting to invest in India has never been simpler, or more accessible. Indian families today have a wide range of instruments available, both traditional and modern:
PPF and NPS India — government-backed, tax-efficient instruments ideal for long-term retirement planning
Mutual funds SIP — flexible, professionally managed, and available with investments as low as ₹500 per month
Fixed Deposits and Recurring Deposits — lower returns but guaranteed and low-risk
Sovereign Gold Bonds — a modern alternative to physical gold, with interest income added
Direct equity — for those willing to research and manage a stock portfolio actively
The wisest approach for most families is portfolio diversification — spreading money across different asset types so that no single loss can derail the whole plan. A mix of traditional vs modern investments, calibrated to the family's risk appetite and time horizon, is the balanced path.
The most important rule: start investing before you feel ready, because the perfect moment never arrives on its own.
Pillar 4: Protecting
Safeguarding everything you have built
The fourth pillar is the most overlooked — and often the most consequential. You can budget beautifully, save consistently, and invest wisely, and still see everything undone by one medical crisis, one premature death, or one unforeseen disaster — if you have not built protection into your financial plan.
Protection has three layers for an Indian family:
Life insurance: The critical distinction here is term life insurance vs an endowment plan. A term plan provides high coverage at a low premium — it is pure protection for your family if you are no longer around to provide for them. An endowment plan mixes insurance with investment and typically delivers poor returns on both. For most families, a term plan is the smarter, more protective choice.
Health insurance: A dedicated family floater policy, not just a rider on a group policy that disappears when you change jobs.
Tax planning: Understanding tax saving under 80C — through instruments like PPF, ELSS mutual funds, and NPS — means keeping more of what you earn, legally and strategically. Every rupee saved in taxes is a rupee that can be reinvested.
Protection is not pessimism. It is the most loving thing a family can do for itself — building a plan that holds even when life does not go according to plan.
Building All Four Pillars Together
Here is the important thing about these four pillars: they are not sequential. You do not finish budgeting before starting to save, or wait until you are fully invested before taking out insurance. They are built simultaneously, in proportion to your current income and life stage.
For a young family just starting, the order of priority typically looks like this:
Get a basic budget in place — know exactly what is coming in and going out
Build an emergency fund of three months' expenses before anything else
Secure a term life insurance policy and basic health cover
Begin a modest SIP — even ₹500 or ₹1,000 per month — and increase it annually
Set SMART financial goals for the next 1, 3, and 10 years and track progress
As income grows, each pillar deepens. The emergency fund grows. The SIP amount increases. The investment mix diversifies. Tax planning becomes more sophisticated. And at each stage, the family becomes a little more resilient, a little more intentional, and a little more secure.
The Bottom Line
Financial security is not a destination you arrive at suddenly. It is a structure you build, one pillar at a time, over years of consistent choices.
Budgeting, saving, investing, and protecting — these are not concepts for wealthy people or finance professionals. They are the fundamental toolkit of personal finance basics that every family in India deserves to understand and use, regardless of income level.
The families that thrive financially are not those who earn the most. They are the ones who built all four walls of their financial house — and kept building, even when life got complicated.
You don't need to be rich to be financially secure. You need to be informed, intentional, and consistent — starting today.