The 50/30/20 Rule Explained Simply — And Why It Works for Indian Households
Introduction
Most people know they should budget. Very few actually do it — not because they are irresponsible, but because most budgeting systems feel like an accounting exam. Spreadsheets with seventeen categories. Apps that require logging every chai and auto-rickshaw ride. Systems so detailed that keeping the system itself becomes a part-time job.
The result? Most people start a budget in January, abandon it by February, and spend the rest of the year vaguely aware that their money is going somewhere — just not quite sure where.
The 50/30/20 budget rule exists to solve exactly this problem. It is the simplest, most durable budgeting framework available — three numbers, three buckets, and a clear direction for every rupee you earn. It does not require a spreadsheet. It does not urge that you track every expense. It only asks that you understand one distinction: needs vs. wants.
Here is everything you need to know to put it to work in your own household — and why it is particularly well-suited to the way Indian families actually manage money.
Where the Rule Comes From
The 50/30/20 rule was popularised by US Senator Elizabeth Warren and her daughter Amelia Warren Tyagi in their 2005 book All Your Worth. The framework was designed to bring simplicity and sustainability to personal finance — creating a system flexible enough to survive real life, and structured enough actually to move people toward financial security.
While it originated in an American context, the underlying logic translates with remarkable ease to Indian households — and with a few thoughtful adjustments, it becomes a deeply practical tool for families across every income bracket in India.
The Three Buckets, Explained
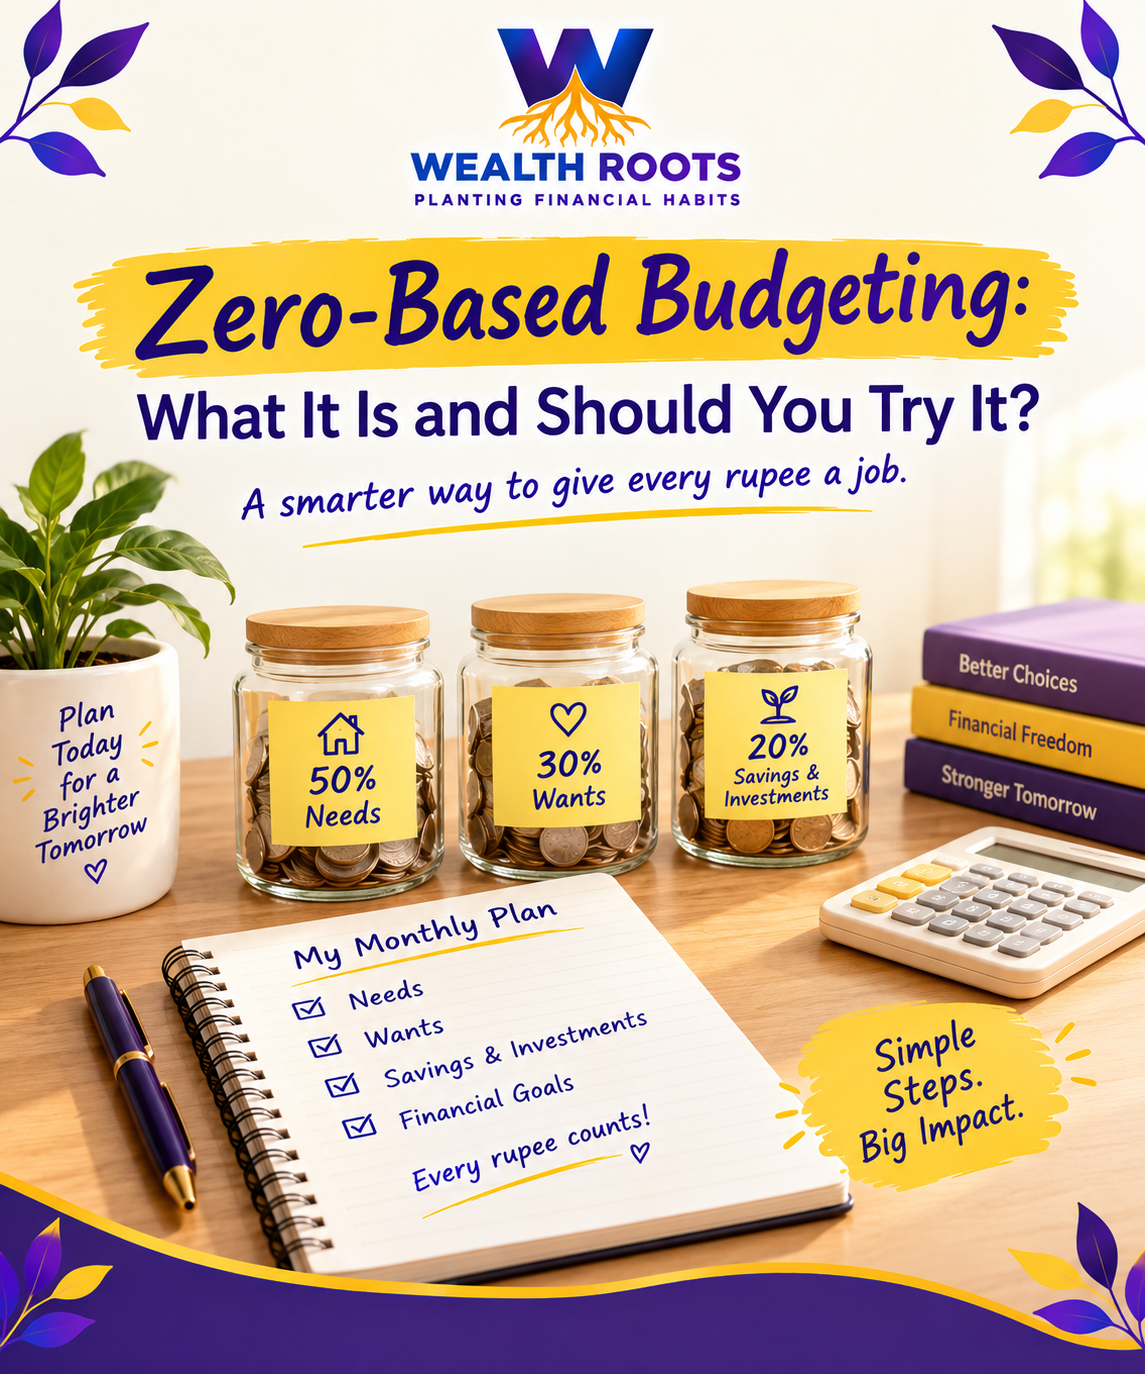
50% — Needs What you cannot do without
The first bucket covers everything essential — expenses that would cause genuine hardship if unpaid. For an Indian household, this typically includes:
Rent or home loan EMI
Groceries and household essentials
Utility bills — electricity, water, gas, internet
School or college fees
Transport to work — fuel, metro pass, auto fare
Essential medical expenses and insurance premiums
Minimum debt repayments if applicable
If 50% of your take-home salary covers all of this comfortably, your financial foundation is stable. If your needs are consistently eating more than 50% — as they do for many families in high-rent cities like Mumbai or Delhi — that is a signal worth addressing: either through income growth, a change in housing, or a review of what is genuinely "essential" versus what has quietly become a fixed habit.
The 50% needs bucket is a mirror — it shows you exactly how much financial breathing room you actually have, before a single want is added.
30% — Wants What makes life enjoyable
This is the bucket most budgeting systems get wrong — either ignoring wants entirely (which makes the budget unsustainable) or leaving them unchecked (which defeats the purpose). The 50/30/20 rule does something smarter: it gives wants a defined, guilt-free space.
Wants are things you choose to spend on because they add quality or joy to your life — not because you cannot live without them. For Indian families, this bucket commonly includes:
Dining out, food delivery, weekend meals at restaurants
OTT subscriptions — Netflix, Prime, Hotstar, SonyLIV
Clothing beyond the basics — fashion, accessories, seasonal updates
Entertainment — movies, concerts, short trips, experiences
Gym memberships, hobbies, personal care beyond essentials
Upgraded versions of things you could buy cheaper — the branded cereal, the premium phone plan
The key insight here is that wants are not bad. They are human. A budget that eliminates all wants is a budget that nobody follows for more than three weeks. The 30% allocation permits you to enjoy your income — within a defined boundary.
For Indian households managing extended family obligations — sending money home, contributing to parents' expenses, funding a sibling's education — these transfers often occupy a grey zone between need and want. A practical approach is to treat regular, committed family support as a need. Occasional or discretionary gifts belong in the wants bucket.
20% — Savings & Investments What builds your future
The third bucket is where financial security is built — and it is the one most Indian households consistently underfund. The 20% allocation covers:
Emergency fund — until you have 3–6 months of expenses set aside
SIP in mutual funds — for long-term wealth creation
PPF contributions — for tax-free retirement savings under 80C
NPS contributions — for structured retirement planning
Recurring Deposits or short-term FDs — for near-term goals like a down payment or a family trip
Additional debt repayment — paying more than the minimum on loans to exit debt faster
The cardinal rule of this bucket is pay yourself first: transfer this 20% on the day your salary arrives, before anything else is spent. When savings are the last thing funded — whatever is left at month-end — they are always the first casualty of an unexpected expense. Automating this transfer through a standing instruction to a SIP or RD ensures it happens without requiring willpower every month.
20% saved and invested consistently is not a sacrifice. Over 15 or 20 years, it is the difference between financial anxiety and financial freedom.
Applying the Rule to an Indian Salary: A Worked Example
Let us bring this to life with real numbers. Consider a household with a combined take-home income of ₹80,000 per month — a fairly representative figure for a dual-income urban family in a Tier 1 or Tier 2 Indian city.
50% — NEEDS: ₹40,000
Rent: ₹18,000
Groceries and household supplies: ₹8,000
School fees (monthly instalment): ₹5,000
Utilities and internet: ₹3,000
Transport: ₹3,000
Insurance premiums (term + health): ₹3,000
30% — WANTS: ₹24,000
Dining out and food delivery: ₹6,000
OTT and subscriptions: ₹1,500
Clothing and personal care: ₹5,000
Entertainment and weekends: ₹4,000
Family support sent home: ₹7,500
20% — SAVINGS & INVESTMENTS: ₹16,000
SIP in equity mutual funds: ₹8,000
PPF contribution: ₹4,000
Emergency fund (RD until target reached): ₹4,000
This is not a perfect household budget — every family's situation differs. But it illustrates how three clear buckets can organise ₹80,000 in a way that covers life today and builds security for tomorrow, without requiring a spreadsheet for every transaction.
Adapting the Rule for Indian Realities
A framework designed in America does not arrive in India without some adjustment. Here are the most common adaptations Indian families find useful:
High-rent cities: In Mumbai, Bengaluru, or Delhi, rent alone can push the needs bucket beyond 50%. In these cases, a 60/20/20 split is a more realistic starting point — the goal is to move toward 50/30/20 progressively as income grows.
Joint family structures: In households where multiple earners pool income or where parents live with the family, apply the rule to the combined take-home figure rather than individual salaries for a more accurate picture.
Irregular income (freelancers, business owners): Apply the rule to your average monthly income over the last three months, and build a larger emergency fund (6–9 months) to buffer lean periods.
Aggressive debt repayment: If you are carrying high-interest debt, temporarily shift to a 50/20/30 split — directing 30% to savings and debt repayment — until the debt is cleared.
Why This Rule Works When Others Don't
Most budgeting systems fail for one of two reasons: they are too complicated to maintain, or too rigid to survive real life. The 50/30/20 rule sidesteps both problems.
It is simple enough to remember without a spreadsheet. It is flexible enough to absorb an unexpected expense or a celebration without requiring a full system reset. And it builds in permission to enjoy money — the 30% wants bucket — which is what makes it sustainable over months and years, not weeks.
More than any other budget-planning framework, it asks the right first question: of all the money I earn, how much is going to my future, how much is allocated to my present, and how much is going to things I genuinely need? When those three numbers are visible and intentional, financial clarity follows.
The Bottom Line
Budgeting does not have to be complicated to be effective. The 50/30/20 rule proves that three numbers, applied consistently, can do more for a family's financial health than the most elaborate spreadsheet ever built.
Start with this month's salary. Identify your needs, your wants, and how much is going toward your future. If the numbers are far from 50/30/20, that is not a failure — it is information. Adjust one bucket at a time, automate your savings transfer on payday, and let the simplicity do the heavy lifting.
Good budget planning tips always point in the same direction: know where your money is going, decide where you want it to go, and close the gap between the two. The 50/30/20 rule is the clearest, most accessible map for that journey — for any Indian household, at any income level.
You don't need to earn more to budget better. You need three numbers, one payday habit, and the discipline to let the system run. Start this month.