Banner Background

Common Money Mistakes

HomeMoney BasicsBudgetingCommon Money Mistakes
Money Basics • Budgeting

Common Money Mistakes

WealthRoots Team
Aug 13, 2026
Common Money Mistakes

The 5 Most Common Money Mistakes and How to Avoid Them

Financial Pitfalls to Avoid in Your 20s and 30s
Building long-lasting wealth isn't just about making brilliant investment decisions; it's equally about avoiding catastrophic bad ones. The financial habits you build in your 20s and 30s will dictate the quality of your life in your 50s and 60s.

Here are the most common financial mistakes people make and exactly how you can avoid them.

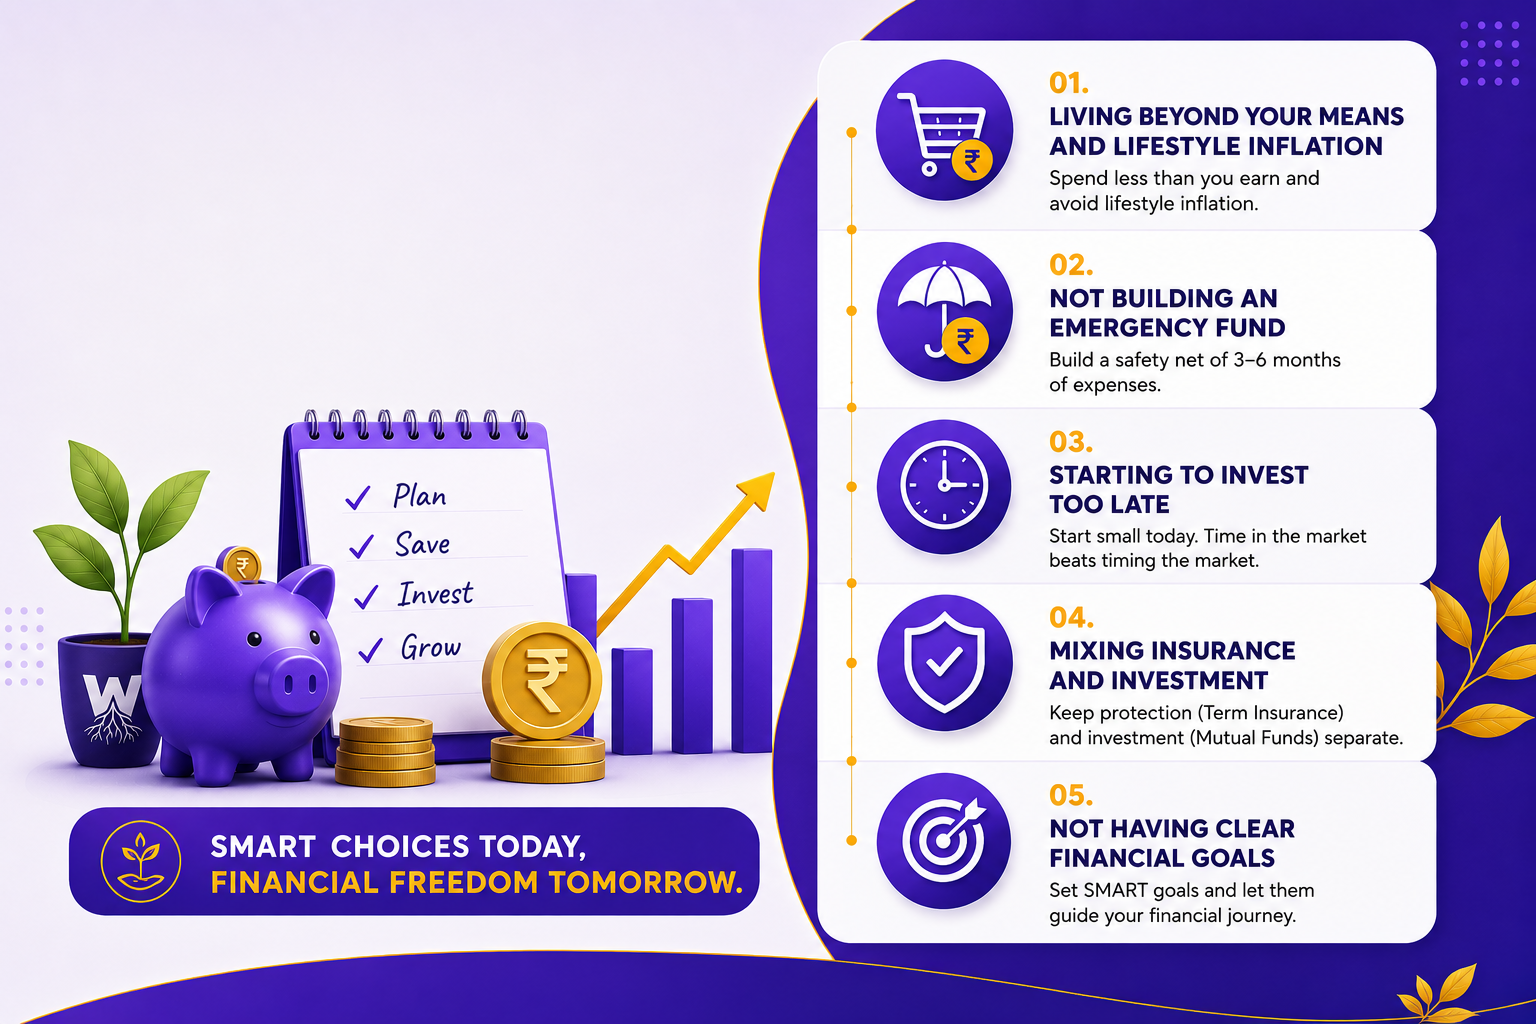
Mistake 1: Living Beyond Your Means and Lifestyle Inflation.
Thanks to easy credit cards, "Buy Now Pay Later" schemes, and EMIs, it is incredibly tempting to buy things you can't afford to keep up with peers on social media. Furthermore, when people get a salary hike, they immediately upgrade their lifestyle—buying a bigger car or an expensive phone. This is called lifestyle inflation, and it prevents you from building wealth.

  • The Fix: Follow the 50/30/20 rule. Allocate 50% of your income for Needs (rent, groceries), 30% for Wants (dining out, entertainment), and strictly save/invest the remaining 20%. When your salary increases, increase your investment amount proportionally.

Mistake 2: Not Building an Emergency Fund
Life is unpredictable. A sudden medical emergency, a sudden job loss, or urgent home repairs can derail your finances instantly if you aren't prepared. If you don't have cash on hand, you will be forced to take high-interest personal loans or sell your long-term investments at a loss.

  • The Fix: Before you invest a single rupee in the stock market, build an emergency fund. Keep at least 3 to 6 months of your mandatory monthly expenses saved in a separate, easily accessible savings account or liquid mutual fund.

Mistake 3: Starting to Invest Too Late
"I'll start investing when I make more money" is the most dangerous financial lie. Many people wait until their late 30s to start investing because they feel their current savings are too small. By waiting, they lose out on their greatest asset - Time.

  • The Fix: Start investing today, even if it is just ₹500 or ₹1000 a month. The magic of compounding works best over long periods. A 25-year-old investing ₹5,000 a month will have significantly more wealth at age 60 than a 35-year-old investing ₹15,000 a month. Time in the market is always more important than timing the market.

Mistake 4: Mixing Insurance and Investment
A classic mistake taught by traditional agents is buying endowment plans, ULIPs, or policies that promise "Life Cover + Guaranteed Returns". These hybrid products are a trap. The life cover they provide is usually too low to protect your family, and the returns are terrible (often barely matching inflation).

  • The Fix: Keep them strictly separate. Buy a pure Term Life Insurance policy for protection (it offers massive coverage for a very low premium). For growing your wealth, invest your money in Mutual Funds or Index Funds.

Mistake 5: Not Having Clear Financial Goals
Investing without a goal is like getting into a taxi and not telling the driver where you want to go. If you don't know why you are saving, you will eventually lose motivation and spend that money impulsively.

  • The Fix: Start by writing down your top three financial goals with a specific amount and deadline. Not “I want to save money” but “I want to build a ₹20 lakh down payment for a home in 5 years” or “I want to create a ₹1 crore retirement corpus by age 55.” These are SMART financial goals — Specific, Measurable, Achievable, Relevant, and Time-bound.

Conclusion

The five mistakes covered in this blog are not rare or unusual — they are the default path that most people follow without realising it. Easy credit encourages lifestyle inflation. The absence of an emergency fund turns every small crisis into a financial setback. Delayed investing quietly costs lakhs in lost compounding. Hybrid insurance products quietly deliver neither adequate protection nor adequate returns. And goalless investing quietly runs out of motivation before it runs out of time.

The good news: every single one of these mistakes is avoidable — not through complexity, but through a few clear, consistent decisions made early and repeated often. Follow the 50/30/20 rule before lifestyle inflation sets in. Build your emergency fund before your first SIP. Start that SIP with ₹500 if that is all you have — and start today. Separate your term insurance from your investments. Write your goals down, attach rupee figures to them, and let those figures guide every financial decision you make.

Financial literacy is not about being perfect with money. It is about being intentional with it — knowing why every rupee is going where it is going, and making sure the answer serves your future, not just your present.
The 5 Most Common Money Mistakes and How to Avoid Them

Financial Pitfalls to Avoid in Your 20s and 30s
Building long-lasting wealth isn't just about making brilliant investment decisions; it's equally about avoiding catastrophic bad ones. The financial habits you build in your 20s and 30s will dictate the quality of your life in your 50s and 60s.

Here are the most common financial mistakes people make and exactly how you can avoid them.

Mistake 1: Living Beyond Your Means and Lifestyle Inflation.
Thanks to easy credit cards, "Buy Now Pay Later" schemes, and EMIs, it is incredibly tempting to buy things you can't afford to keep up with peers on social media. Furthermore, when people get a salary hike, they immediately upgrade their lifestyle—buying a bigger car or an expensive phone. This is called lifestyle inflation, and it prevents you from building wealth.

  • The Fix: Follow the 50/30/20 rule. Allocate 50% of your income for Needs (rent, groceries), 30% for Wants (dining out, entertainment), and strictly save/invest the remaining 20%. When your salary increases, increase your investment amount proportionally.

Mistake 2: Not Building an Emergency Fund
Life is unpredictable. A sudden medical emergency, a sudden job loss, or urgent home repairs can derail your finances instantly if you aren't prepared. If you don't have cash on hand, you will be forced to take high-interest personal loans or sell your long-term investments at a loss.

  • The Fix: Before you invest a single rupee in the stock market, build an emergency fund. Keep at least 3 to 6 months of your mandatory monthly expenses saved in a separate, easily accessible savings account or liquid mutual fund.

Mistake 3: Starting to Invest Too Late
"I'll start investing when I make more money" is the most dangerous financial lie. Many people wait until their late 30s to start investing because they feel their current savings are too small. By waiting, they lose out on their greatest asset - Time.

  • The Fix: Start investing today, even if it is just ₹500 or ₹1000 a month. The magic of compounding works best over long periods. A 25-year-old investing ₹5,000 a month will have significantly more wealth at age 60 than a 35-year-old investing ₹15,000 a month. Time in the market is always more important than timing the market.

Mistake 4: Mixing Insurance and Investment
A classic mistake taught by traditional agents is buying endowment plans, ULIPs, or policies that promise "Life Cover + Guaranteed Returns". These hybrid products are a trap. The life cover they provide is usually too low to protect your family, and the returns are terrible (often barely matching inflation).

  • The Fix: Keep them strictly separate. Buy a pure Term Life Insurance policy for protection (it offers massive coverage for a very low premium). For growing your wealth, invest your money in Mutual Funds or Index Funds.

Mistake 5: Not Having Clear Financial Goals
Investing without a goal is like getting into a taxi and not telling the driver where you want to go. If you don't know why you are saving, you will eventually lose motivation and spend that money impulsively.

  • The Fix: Start by writing down your top three financial goals with a specific amount and deadline. Not “I want to save money” but “I want to build a ₹20 lakh down payment for a home in 5 years” or “I want to create a ₹1 crore retirement corpus by age 55.” These are SMART financial goals — Specific, Measurable, Achievable, Relevant, and Time-bound.

Conclusion

The five mistakes covered in this blog are not rare or unusual — they are the default path that most people follow without realising it. Easy credit encourages lifestyle inflation. The absence of an emergency fund turns every small crisis into a financial setback. Delayed investing quietly costs lakhs in lost compounding. Hybrid insurance products quietly deliver neither adequate protection nor adequate returns. And goalless investing quietly runs out of motivation before it runs out of time.

The good news: every single one of these mistakes is avoidable — not through complexity, but through a few clear, consistent decisions made early and repeated often. Follow the 50/30/20 rule before lifestyle inflation sets in. Build your emergency fund before your first SIP. Start that SIP with ₹500 if that is all you have — and start today. Separate your term insurance from your investments. Write your goals down, attach rupee figures to them, and let those figures guide every financial decision you make.

Financial literacy is not about being perfect with money. It is about being intentional with it — knowing why every rupee is going where it is going, and making sure the answer serves your future, not just your present.
Request a Callback

Leave your details below and our team will get back to you shortly.

Common Money Mistakes | WealthRoots Blog