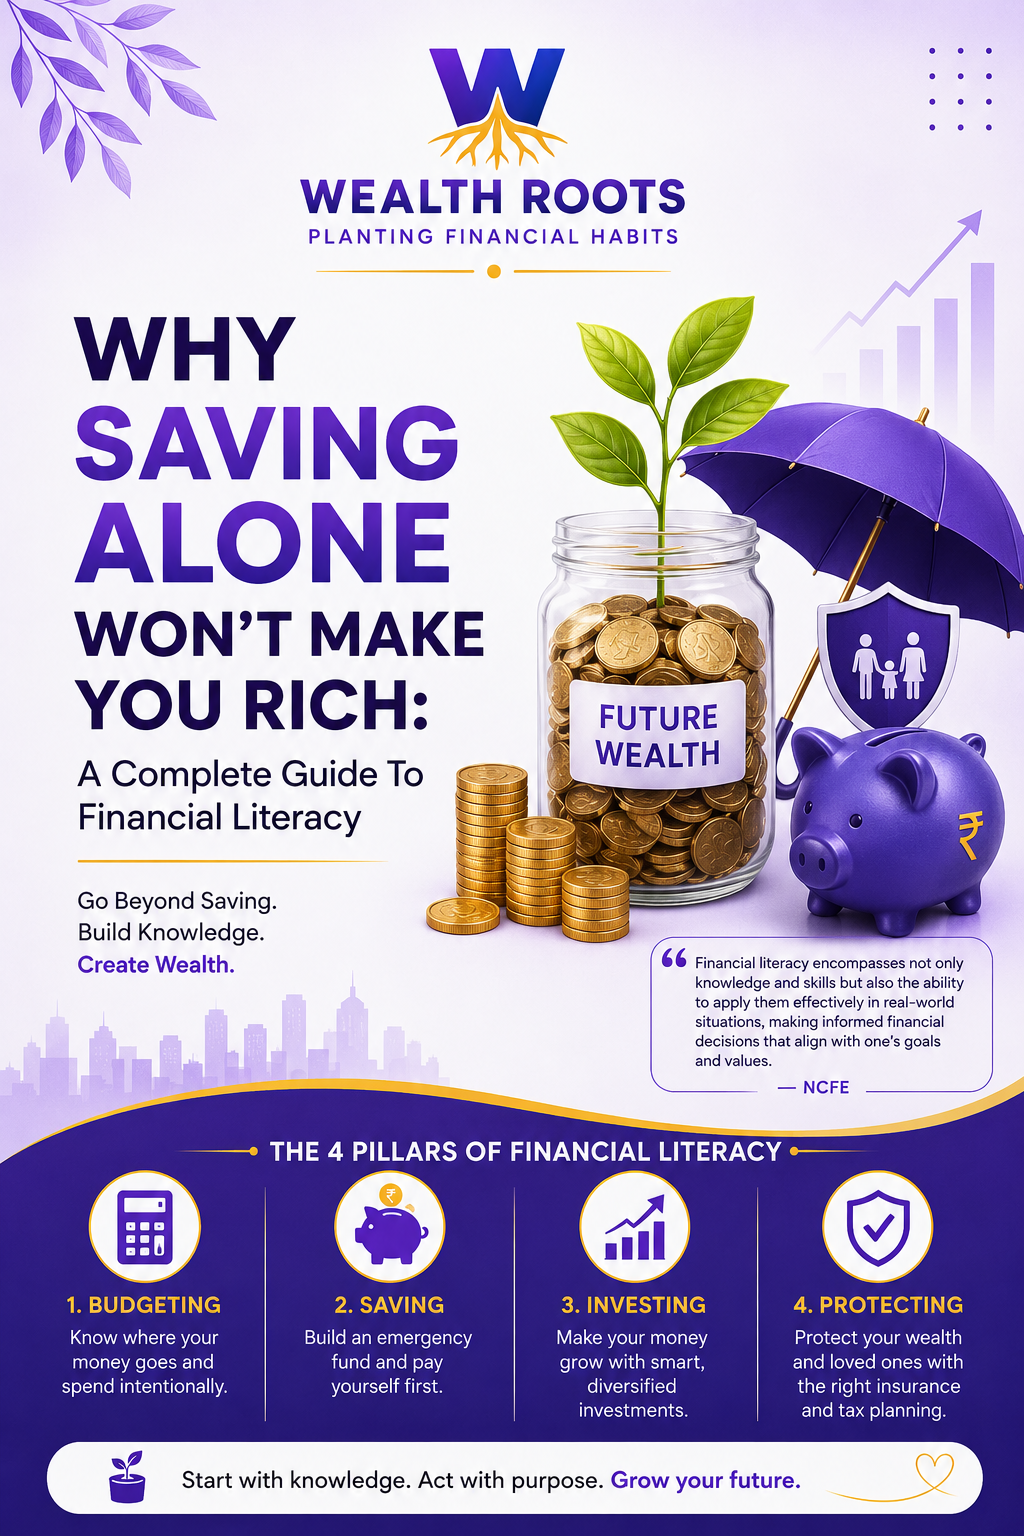
Why Saving Alone Won’t Make You Rich: A Complete Guide To Financial Literacy
Introduction
Your grandmother kept cash under the mattress. Your parents opened an FD the moment they received their first salary. And you were probably told, growing up, that saving is the most important thing you can do with money.
That advice wasn't wrong. But it wasn't complete either!
Saving is one tool in a much larger toolkit. If saving were enough, every disciplined saver in India would retire wealthy. But we know that isn't the case. Inflation silently erodes the value of money sitting idle in a savings account. And a lifetime of hard-earned savings can still leave you financially vulnerable if it isn't protected, invested, and grown.
This is what financial literacy is really about — and it goes far beyond savings.
What Is Financial Literacy?
Financial literacy is the set of knowledge, skills, and behaviours that help you make informed decisions about money — decisions that align with your goals, your family's needs, and your long-term security.
It is not just about knowing what a mutual fund is or understanding that you should spend less than you earn. True financial knowledge and skills mean you can:
Earn more strategically — through salary negotiation, side income, or entrepreneurship
Spend intentionally — distinguishing needs vs wants before swiping that card
Save purposefully — building an emergency fund before anything else
Borrow responsibly — understanding the real cost of an EMI or credit card balance
Invest wisely — making your money work as hard as you do
"Financial literacy encompasses not only knowledge and skills but also the ability to apply them effectively in real-world situations, making informed financial decisions that align with one's goals and values." — NCFE |
The Problem with Savings-Only Thinking
Consider this: if you save ₹5,000 every month in a savings account offering a yearly interest of 3.5%, in 20 years you will have approximately ₹17.4 lakhs.
Now consider starting a SIP of ₹500 per month in an equity mutual fund that historically delivers 12% annually. In 20 years? You would have built a corpus of over ₹4.9 lakhs — from just ₹500 a month. Scale that to ₹5,000 per month in the same SIP, and you are looking at nearly ₹49 lakhs — almost three times what the savings account delivers.
This is the power of compounding — and it only works when your money is invested, not just saved.
This is not to say saving is bad. It is essential. But saving is the foundation, not the whole house.
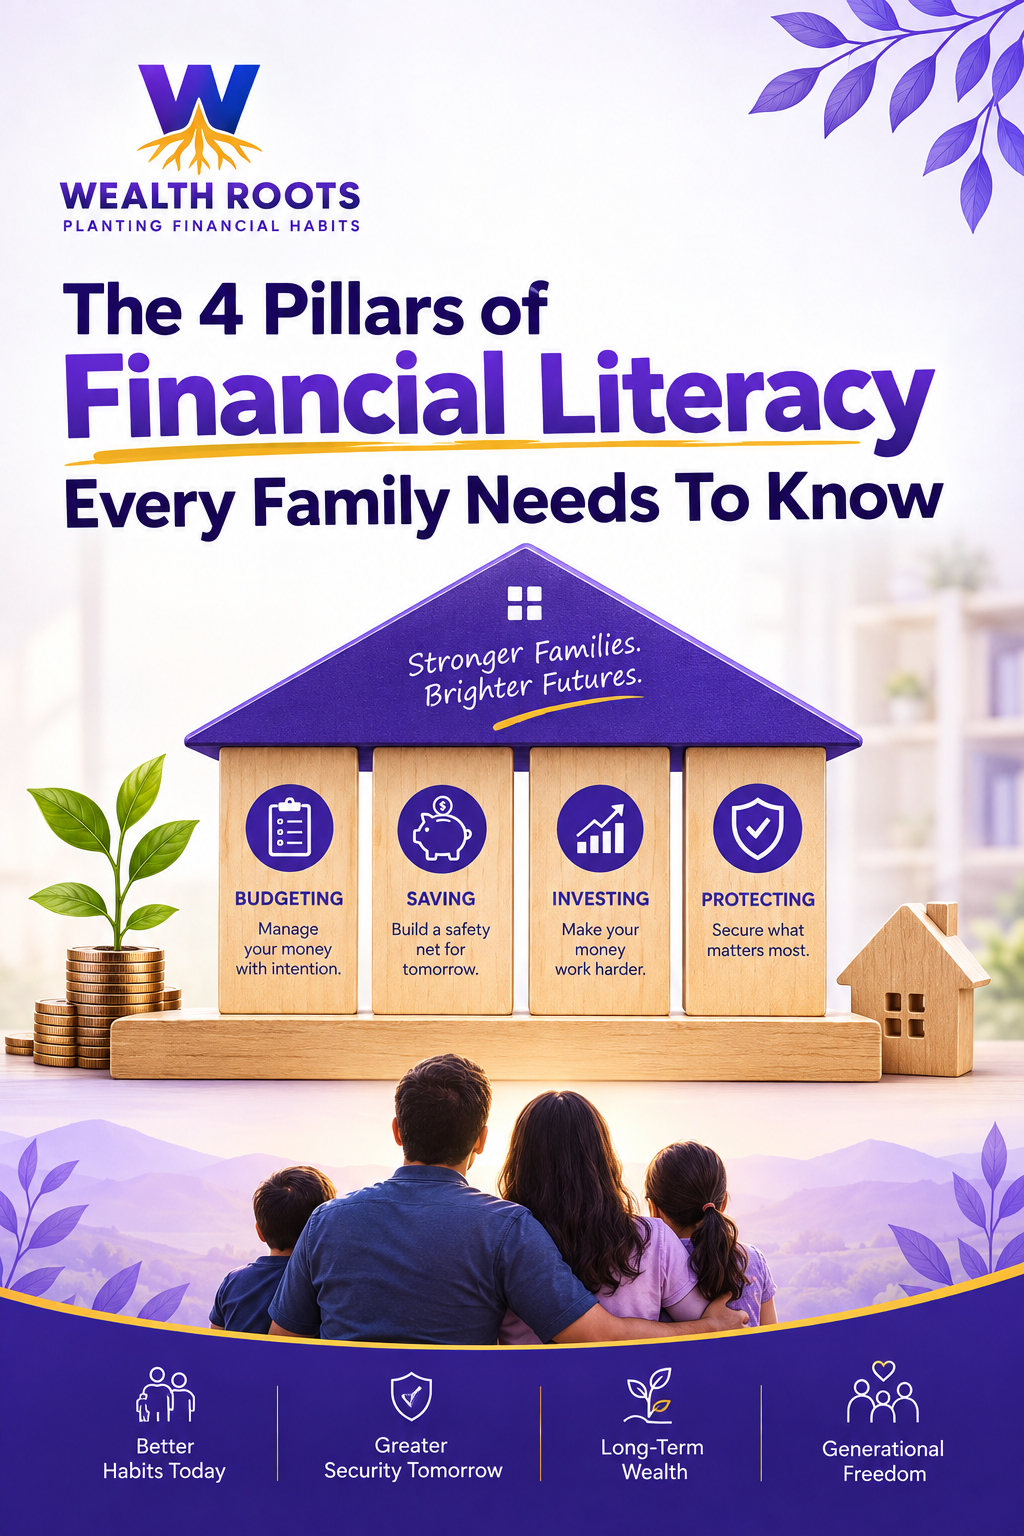
The 4 Pillars of Financial Literacy
A complete approach to personal finance rests on four pillars. Think of them as the four walls of your financial home — remove any one, and the structure weakens.
PILLAR 1 — BUDGETING
Before you can save or invest, you need to know where your money is going. The 50/30/20 budget rule is one of the simplest frameworks for Indian households: 50% of income goes to needs (rent, groceries, utilities), 30% to wants (dining out, subscriptions, travel), and 20% to savings and investments.
Good budget planning tips always start with tracking expenses for one month before making any changes. You cannot fix what you cannot see.
PILLAR 2 — SAVING
Saving is not just about accumulating money — it is about paying yourself first. Before your rent, before your groceries, before Netflix — set aside a fixed amount for your future self.
The first savings goal for every individual should be an emergency fund — three to six months of living expenses, kept liquid in a savings account or short-term FD. This is your financial safety net.
PILLAR 3 — INVESTING
Once your emergency fund is in place, your money should start working for you. This is where traditional vs modern investments come into the picture.
Traditional: PPF and NPS India, Fixed Deposits, Post Office Schemes, and physical gold
Modern: Mutual funds, SIP, ETFs, Sovereign Gold Bonds, direct equity, REITs
Neither is universally better. Portfolio diversification — spreading money across different asset types — is the safest long-term strategy. The key is to start. You can begin a SIP with ₹500 per month and build from there.
PILLAR 4 — PROTECTING
Everything you save and invest can be wiped out by one medical emergency, one accident, or one unforeseen loss — unless you have protection in place.
This means having the right insurance (a term life insurance vs endowment plan comparison will surprise most people — term plans offer far more coverage at a fraction of the cost) and understanding tax savings under 80C to keep more of what you earn.
Why Financial Literacy Matters More Now Than Ever
India's economy is changing rapidly. UPI digital payments in India have transformed how we spend money — making it faster, easier, and far less visible. The rise of BNPL (Buy Now Pay Later) schemes has made debt dangerously accessible, especially for young people.
At the same time, the gig economy means more Indians than ever are self-employed — with no EPF contributions automatically going in, no employer-managed health cover, and no guaranteed income during illness or downtime.
In this environment, financial literacy is not optional. It is protective.
The National Centre for Financial Education (NCFE) and the National Strategy for Financial Education (NSFE) exist precisely because India recognises that financial knowledge must reach every citizen — not just the wealthy or the formally educated.
How to Start Investing in India — Even If You Are a Beginner
The most common reason people don't invest is that they think they don't have enough money or don't know enough. Both are myths.
Here is a simple starting path:
Step 1: Build your emergency fund — 3 months of expenses in a savings account
Step 2: Get adequate term life insurance coverage if you have dependents
Step 3: Start a SIP with ₹500 per month in a diversified equity mutual fund
Step 4: Open a PPF account for long-term, tax-free savings
Step 5: Set SMART financial goals — specific, measurable, and time-bound
Over time, as your income grows, increase your investment amount. This systematic habit — started early, maintained consistently — is how generational financial security is built.
The Bottom Line
Saving is a habit. Financial literacy is a life skill.
One keeps your money safe. The other makes it grow, protects it from inflation, shields it from risk, and helps it outlast you — becoming something you can pass on to the people you love.
Whether you are a woman building economic independence, a parent wanting to raise money-smart children, or a young professional trying to figure out where to start, the answer is the same: start with knowledge, then act on it.
Financial literacy is not a one-time lesson. It is a lifelong journey — and the best time to begin is today.