Zero-Based Budgeting: What It Is and Should You Try It?
Introduction
Most people who budget do it the same way: salary arrives, bills get paid, a few things get bought, and whatever survives to the end of the month — if anything does — gets called savings. It is reactive, unintentional, and almost universally unsatisfying.
There is a better way. And it starts with a deceptively simple question that most people never think to ask about their own money:
Why am I spending this? Not just what am I spending it on — but why does this expense deserve a place in my financial life this month?
This is the animating question behind zero-based budgeting (ZBB) — a method that requires you to justify every rupee of spending from scratch, every single month. It is more demanding than the 50/30/20 budget rule. It is also, for the right person in the right situation, more powerful.
This blog explains exactly what zero-based budgeting is, how to build one, what it does exceptionally well, and — honestly — who it is not right for.
What Is Zero-Based Budgeting?
Zero-based budgeting is a budgeting method in which every rupee of income is assigned a specific job — until the total income minus total assigned expenses equals exactly zero. Not because you have spent everything, but because every rupee has been deliberately directed somewhere: rent, groceries, SIP, emergency fund, school fees, dining out, savings goals.
The name comes from the starting point: zero. Unlike conventional budgeting — where last month's budget is rolled forward with minor tweaks — zero-based budgeting starts from scratch every month. You do not assume that last month's ₹3,000 entertainment budget gets ₹3,000 again this month. Every category must earn its place in the new month's plan.
In practice, the equation looks like this:
Monthly Income − All Assigned Expenses = ₹0
If you earn ₹60,000 this month, every rupee of that ₹60,000 is named before the month begins — ₹15,000 for rent, ₹7,000 for groceries, ₹5,000 for the SIP, ₹2,000 for dining out, and so on. When the total reaches ₹60,000, the budget is complete. Nothing is left unnamed, nothing is left to chance.
Crucially, "assigned to savings" counts. You are not trying to spend every rupee — you are trying to give every rupee a destination. ₹10,000 assigned to your mutual fund SIP is just as valid an assignment as ₹10,000 assigned to rent.
How to Build a Zero-Based Budget: Step by Step
Step 1: Start with Your Actual Take-Home Income
Begin with the money that actually lands in your account — after taxes, after EPF deductions, after any other automatic deductions. If your income varies month to month (as it does for freelancers, consultants, or commission-based earners), use the lowest of the last three months as your baseline. Building on a conservative estimate protects you from overspending in lean months.
If you have multiple income sources — salary, rental income, side income, spouse's income — add them all together for a single monthly income figure.
Step 2: List Every Expense Category You Can Think Of
Go broad here. Write down every category of spending that appears in your life — not just the obvious ones. Include:
Fixed needs: rent/EMI, school fees, insurance premiums, loan repayments
Variable needs: groceries, electricity, water, fuel, medicine
Savings and investments: SIP, PPF, NPS, emergency fund, FD
Wants: dining out, entertainment, subscriptions, clothing, personal care
Irregular expenses: car service, annual subscriptions, festival shopping, medical check-ups
Family obligations: money sent home, parents' support, gifts
The irregular expenses category is where most budgets have a hidden leak. Annual expenses divided by 12 give you a monthly provision to set aside — so a ₹12,000 annual car service becomes ₹1,000 per month in the budget, sitting quietly in a sinking fund until it is needed.
Step 3: Assign Every Rupee a Job
Now comes the core of zero-based budgeting. Go through each category and assign an amount — starting with your non-negotiable needs and savings goals, then moving to wants, then to irregular provisions.
The critical discipline: savings and investments must be assigned before wants. This is the pay-yourself-first principle built structurally into the budget — not as an aspiration, but as a hard line. Your SIP gets its ₹5,000 before the dining-out category gets a single rupee.
Keep subtracting from your total income as you assign each category. When you reach zero — when every rupee is accounted for — your budget is complete. If you run out of income before running out of categories, something must be reduced or removed. If you finish with money still unassigned, it must be directed somewhere intentional: an additional SIP contribution, a higher emergency fund deposit, or a named savings goal.
Step 4: Track and Reconcile Through the Month
A zero-based budget only works if you track actual spending against the plan. This does not require logging every ₹20 chai — it requires a weekly 10-minute check-in where you compare what was spent in each category against what was assigned.
When a category is overspent, the money must come from somewhere else — not from savings. This trade-off awareness is what makes zero-based budgeting genuinely educational: it forces real-time decisions about priorities, rather than letting overspending silently absorb whatever is left.
Step 5: Reset and Rebuild at the Start of Every Month
Every new month, every category starts at zero again. Last month's unspent dining-out budget does not automatically roll forward. You decide, fresh, how much each category deserves this month — based on this month's income, this month's priorities, and this month's known commitments.
This monthly reset is ZBB's most powerful feature and its most demanding requirement. It is what keeps the budget alive and current — and what makes it feel like work.
A Quick Example: ₹50,000 Monthly Income
Here is how a zero-based budget might look for a single professional earning ₹50,000 take-home per month in a Tier 2 city:
Rent: ₹12,000
Groceries and household: ₹5,500
Utilities and internet: ₹2,500
Transport: ₹2,000
Insurance premium (term + health): ₹2,000
SIP — equity mutual fund: ₹6,000
PPF contribution (monthly equivalent): ₹2,000
Emergency fund top-up: ₹2,000
Dining out: ₹3,500
Entertainment and subscriptions: ₹2,000
Clothing and personal care: ₹2,500
Family support: ₹3,000
Irregular expense provision (sinking fund): ₹1,500
Miscellaneous buffer: ₹1,000
Total: ₹49,000.
The remaining ₹1,000 is assigned to the emergency fund rather than left untracked.
Budget: ₹50,000 − ₹50,000 = ₹0.
Every rupee has a job.
Zero-Based Budgeting vs. the 50/30/20 Rule: Which Is Better?
Neither is universally better. They solve different problems for different people.
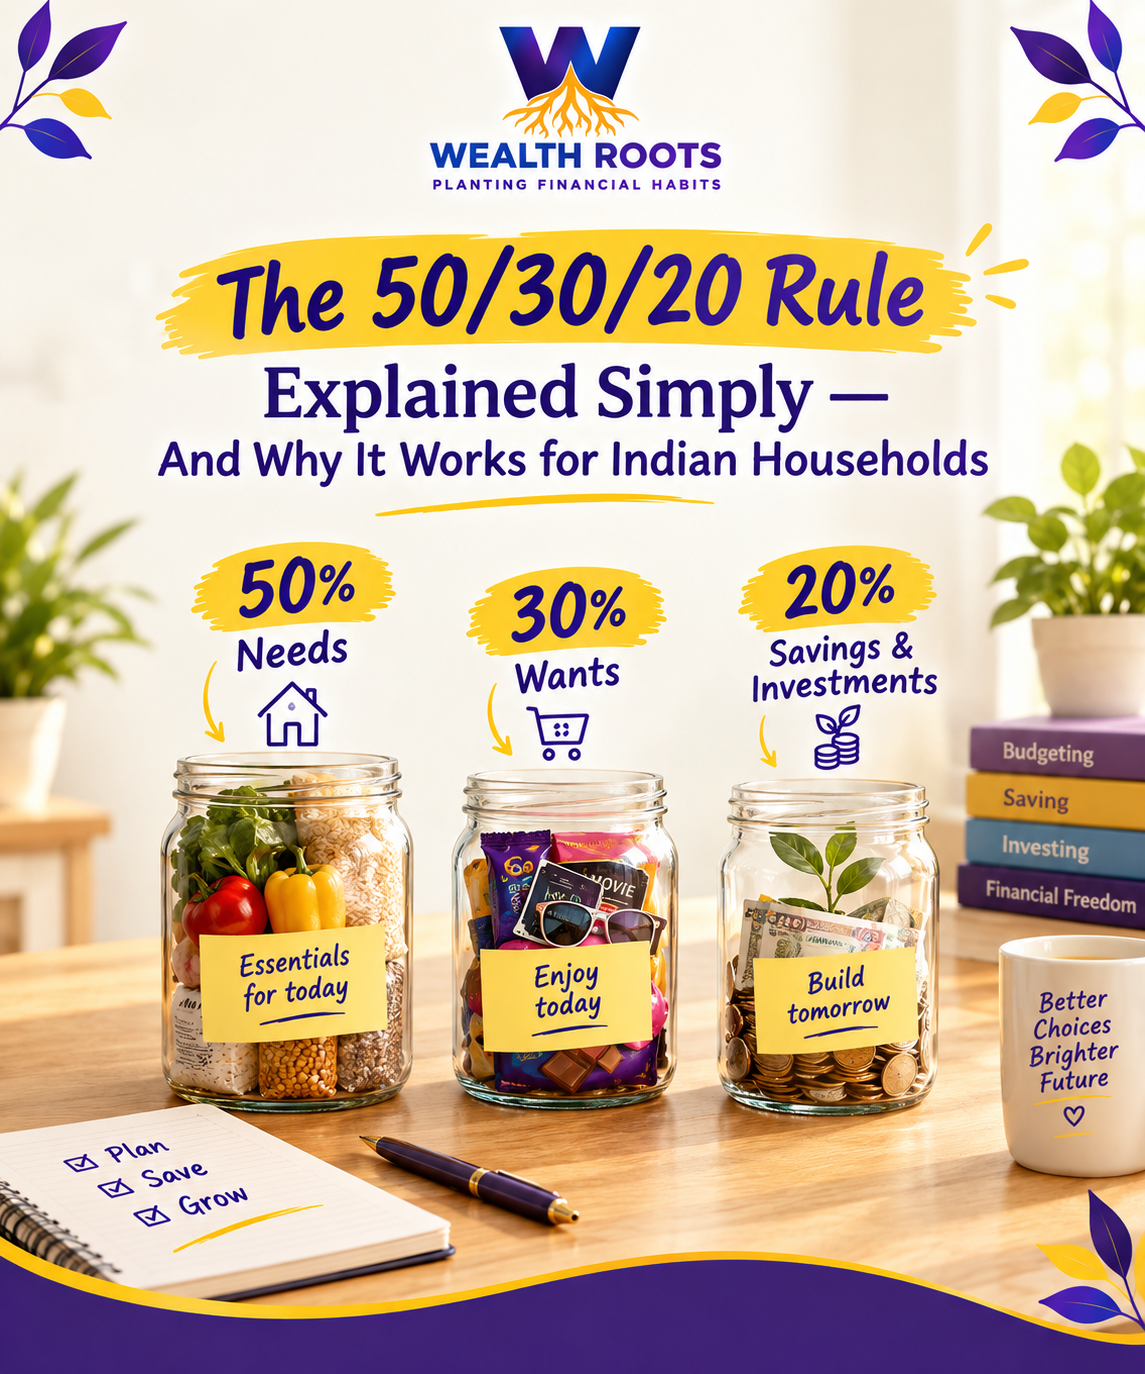
The 50/30/20 budget rule is ideal for beginners, busy households, and anyone who wants a simple, durable framework that does not require significant time investment. Three buckets, one payday transfer, done.
Zero-based budgeting is better suited to people who want granular control, those trying to identify and eliminate specific spending leaks, households with irregular income that cannot rely on fixed percentages, and anyone who finds that broad categories let too much slip through unnoticed.
A practical approach many people use: start with 50/30/20 to build the budgeting habit, then shift to zero-based budgeting once you are ready for deeper financial intentionality — or during a specific period of financial pressure where every rupee genuinely matters.
50/30/20 gives you direction. Zero-based budgeting gives you a destination — with every rupee knowing exactly where it is going and why.
Is Zero-Based Budgeting (ZBB) Right for You?
ZBB WORKS WELL FOR
People who have tried simpler budgets and still cannot identify where money disappears
Households managing debt aggressively — where every rupee redirected to repayment accelerates freedom
Freelancers and business owners with variable income who need to consciously re-plan each month
Couples aligning on financial priorities for the first time — ZBB makes all assumptions visible and negotiable
Anyone who has SMART financial goals and wants the budget to actively reflect and fund them
ZBB MAY NOT BE RIGHT FOR
Absolute beginners — start with 50/30/20, build the habit, then graduate to ZBB
People with highly stable, predictable expenses who would find monthly rebuilding unnecessarily effortful
Those in highly stressful financial periods where complexity adds anxiety rather than clarity — simplicity first
The Bottom Line
Zero-based budgeting is not the easiest approach to personal finance — but it may be the most honest one. It removes the comfortable fiction that last month's spending was fine simply because you survived it. It demands that every rupee justify its place. And in doing so, it quietly builds the financial knowledge and skills that separate people who manage money from people who are managed by it.
If you have ever reached the end of a month wondering where your salary went — despite earning a reasonable income — zero-based budgeting is worth trying. Not forever, perhaps. But for one month, with full commitment, it will show you more about your financial habits than years of vague awareness ever could.
Give every rupee a name. Watch what changes.
A budget is not a restriction on your life. It is a plan for it. Zero-based budgeting simply makes that plan as precise and intentional as your money deserves.