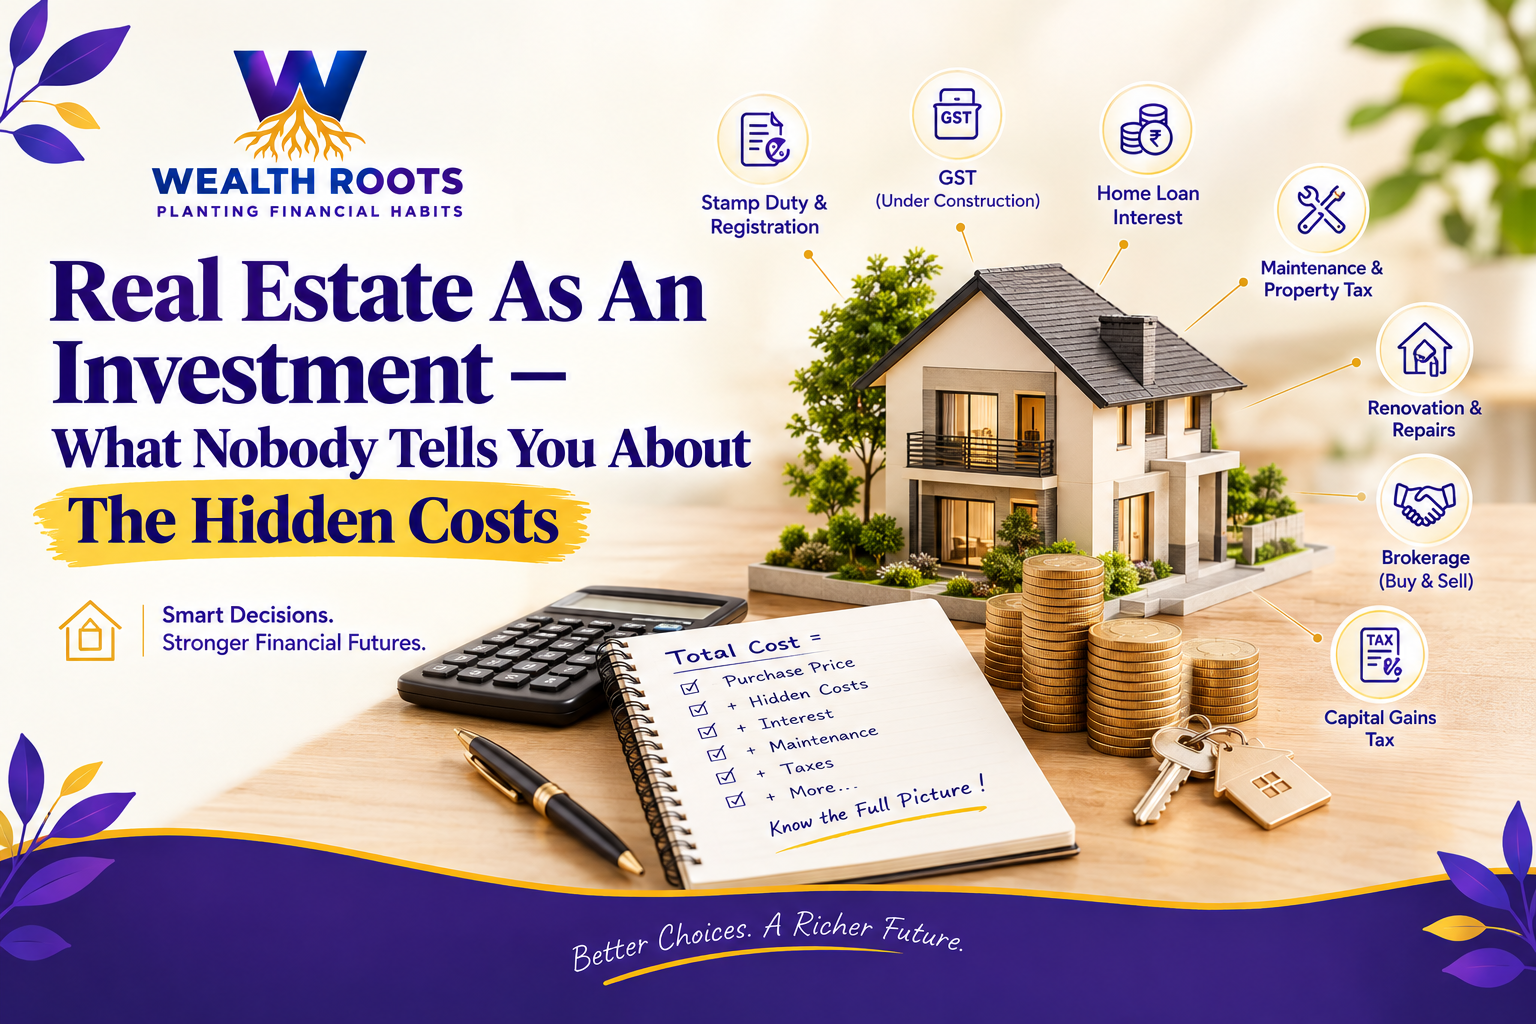
Real Estate As An Investment — What Nobody Tells You About The Hidden Costs
Introduction
Ask any Indian family what their most reliable investment is, and the answer will almost always be the same: property. Real estate sits at the centre of how most Indians think about wealth — it is tangible, permanent, and carries the deep cultural conviction that land and buildings always go up in value.
And there is truth in that belief. Real estate has created significant wealth for many Indian families, particularly those who bought in the right locations at the right time. Property in Mumbai, Bengaluru, Hyderabad, and Pune has delivered extraordinary appreciation over the past two decades.
But here is what the property brochures, the builders, and the enthusiastic uncles at family gatherings never quite get around to mentioning: real estate is one of the most expensive assets to buy, hold, and sell — and the hidden costs embedded in every stage of that journey can dramatically alter the actual return on your investment.
This blog is about bringing those costs to light - so you can make a genuinely informed decision rather than an emotionally comfortable one.
The Price Tag You See — and the One You Don't
When someone says they bought a flat for ₹60 lakhs, that is rarely what they actually paid. The sticker price of a property is just the starting point of a long list of costs that most buyers discover only after the deal is done.
Let us walk through what a ₹60 lakh property purchase actually costs, layer by layer.
1. Stamp Duty and Registration Charges
Stamp duty in India varies by state — typically between 4% and 8% of the property value, with women buyers sometimes eligible for a 1–2% concession in certain states. Registration charges add another 1%. On a ₹60 lakh property, this means ₹3–5 lakhs paid upfront to the government, before you have received a single key.
This amount is non-negotiable, non-refundable, and adds zero to the property's resale value. It is the first hidden cost most buyers underestimate.
2. GST on Under-Construction Properties
If you are buying an under-construction flat directly from a builder, GST applies at 5% of the property value (1% for affordable housing under defined limits). On a ₹60 lakh property, that is ₹3 lakhs added to your cost — again, recoverable nowhere.
Ready-to-move-in properties are exempt from GST, which is one reason they are often preferred — though they typically carry a higher sticker price to compensate.
3. Home Loan Interest — The Silent Giant
Most property purchases in India are financed through home loans, and the total interest paid over a 20-year loan tenure is a cost so high it is almost shocking when calculated in full.
On a ₹48 lakh home loan (80% of ₹60 lakhs) at 8.5% interest over 20 years, the total interest paid is approximately ₹52–54 lakhs — nearly equal to the original loan principal itself. Your ₹60 lakh property - by the time the loan is fully repaid - has cost you well over ₹1 crore when all payments are totalled.
This does not make buying a home a bad decision — homeownership has genuine value beyond investment returns. But it is a number every buyer deserves to see before signing.
The price of a property is what you pay once. The cost of a property is what you pay over a lifetime. These are rarely the same number.
4. Maintenance, Society Charges, and Property Tax
Once you own a property, the costs do not stop — they simply change form. Every residential society in India charges monthly maintenance fees typically around ₹2,000–8,000 per month in urban areas, higher in gated communities with amenities.
Over 20 years, at a conservative ₹3,000 per month, that is ₹7.2 lakhs in maintenance charges alone — before accounting for inflation-linked increases that most societies apply annually.
Add property tax (charged by the municipal corporation, typically 0.1–0.3% of property value per year), and you have a recurring annual cost of ₹6,000–18,000 simply for the privilege of owning the asset.
5. Renovation, Repairs, and Interior Costs
A newly purchased property is rarely move-in ready without investment. Flooring upgrades, kitchen fittings, painting, bathroom fixtures, electrical work, and basic furniture typically add ₹3–10 lakhs to a flat cost, depending on size and finishes.
Over a holding period of 15–20 years, at least one significant renovation cycle is expected — replastering walls, replacing plumbing, upgrading electrical wiring — adding another ₹3–5 lakhs at minimum.
6. Brokerage on Purchase and Sale
Real estate agents charge brokerage on both ends of a transaction — typically 1–2% of property value from the buyer, and 1–2% from the seller. On a ₹60 lakh purchase and a later sale at ₹1 crore (assuming appreciation), total brokerage across both transactions can amount to ₹2.2–4 lakhs.
7. Capital Gains Tax on Sale
When you eventually sell the property, the profit is subject to capital gains tax. For properties held over 24 months, Long Term Capital Gains (LTCG) tax applies at 12.5% on the indexed gain (post the 2024 budget revision, removing the indexation benefit for most sellers). On a significant appreciation, this can mean lakhs paid to the government at the point of exit.
Exemptions exist — reinvesting gains in another property under Section 54, or in specified bonds under Section 54EC — but these come with their own conditions and lock-ins.
The Full Cost Picture: A Reality Check
Adding up the hidden and visible costs on a ₹60 lakh property purchased with a home loan and held for 20 years, a conservative estimate looks something like this:
Stamp duty and registration: ₹3.5–5 lakhs
GST (if under-construction): ₹3 lakhs
Total home loan interest over 20 years: ₹52–54 lakhs
Maintenance and property tax over 20 years: ₹9–12 lakhs
Renovation and repairs over the holding period: ₹6–12 lakhs
Brokerage on purchase and eventual sale: ₹2.5–4 lakhs
Capital gains tax on sale profit: variable, potentially ₹5–15 lakhs
Total additional cost beyond the purchase price: ₹76–1 crore+ — meaning a ₹60 lakh property can realistically cost ₹1.4–1.6 crore by the time all outflows are accounted for over its lifetime.
For that investment to break even, the property needs to appreciate to at least ₹1.4–1.6 crore. For it to outperform a diversified investment portfolio, it needs to perform significantly better.
What Real Estate Does Well — and What It Doesn't
None of this means real estate is a bad investment. It means it is a specific kind of investment, with specific strengths and specific blind spots.
WHERE REAL ESTATE WORKS
As a long-term asset in high-growth urban corridors with genuine demand
As a self-occupied home — where the emotional and lifestyle value justifies the financial cost
As rental income — generating yield while the asset appreciates, though rental yields in India are typically just 2–3% per year
As an inheritance asset — property passes more intuitively across generations than financial instruments for many families
WHERE REAL ESTATE STRUGGLES
Liquidity — you cannot sell 10% of a flat in an emergency the way you can redeem part of a mutual fund
Concentration risk — a large portion of net worth in a single illiquid asset is a significant financial vulnerability
Management — unlike a SIP, property requires active management: tenants, repairs, legal compliance, society disputes
Transaction costs — the high entry and exit costs mean short-to medium-term holding rarely makes financial sense
Real estate rewards patience, location intelligence, and full-cost awareness. Entered without these three, it can quietly consume more wealth than it creates.
The Alternative Worth Knowing About: REITs
For investors who want real estate exposure without the capital intensity, illiquidity, and hidden costs, Real Estate Investment Trusts (REITs) are worth understanding. Listed on Indian stock exchanges since 2019, REITs allow investors to own a fractional interest in commercial real estate — office parks, malls, warehouses — with investments starting at a few hundred rupees.
REITs regulated by SEBI offer regular dividend income (typically 6–8% yield), and can be bought and sold like shares — providing the liquidity that direct property ownership fundamentally lacks. They are not a perfect substitute for owning a home, but for the investment portion of a real estate allocation, they deserve serious consideration.
The Bottom Line
Real estate will remain a cornerstone of how Indian families think about wealth — and it should. Land and property have real, enduring value. The problem is not the asset. The problem is the incomplete picture most buyers carry into one of the largest financial decisions of their lives.
The hidden costs of real estate are not hidden by accident. They are distributed across time, across different parties, and across different stages of ownership — making them easy to overlook individually, and shocking when totalled. Portfolio diversification means not letting one asset class — however familiar and reassuring — consume a disproportionate share of your wealth and your financial flexibility.
Buy property with your eyes fully open: to the stamp duty, the loan interest, the maintenance years, the tax on exit, and the illiquidity in between. When you know the full cost, you can make a genuinely good decision — whether that decision is to buy, to wait, or to invest differently.
The best investment is always an informed one. In real estate, being informed means knowing not just the price — but everything that comes after it.